dant555/flipfinder-usa
收藏资源简介:
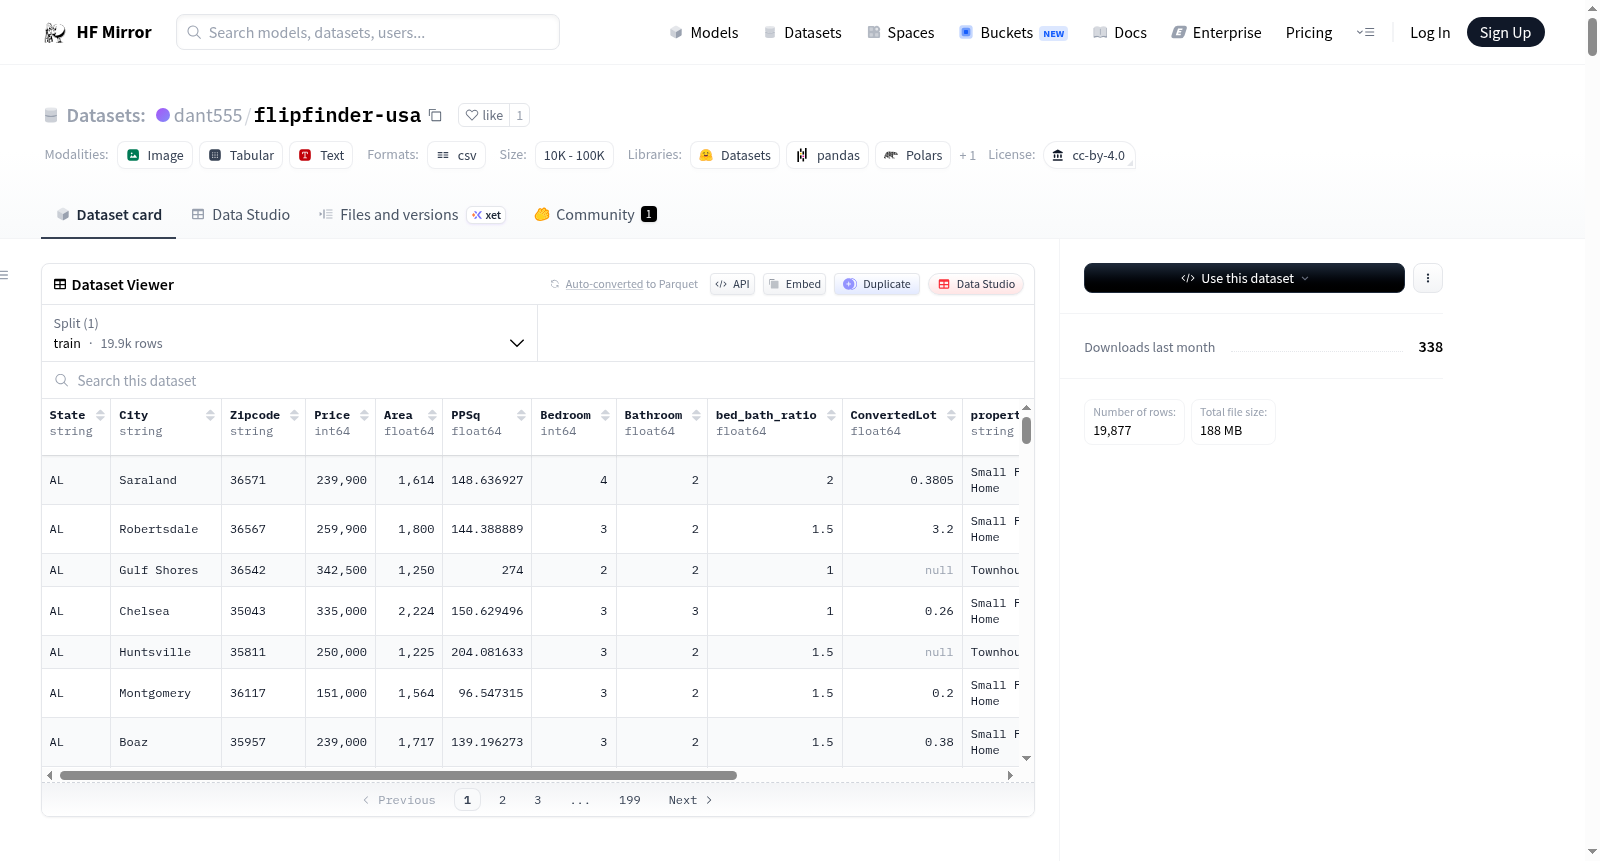
--- license: cc-by-4.0 configs: - config_name: default data_files: - split: train path: flipfinder_usa_cleaned.csv default_config: true features: - name: State dtype: string - name: City dtype: string - name: Zipcode dtype: string - name: Price dtype: int64 - name: Area dtype: float64 - name: PPSq dtype: float64 - name: Bedroom dtype: int64 - name: Bathroom dtype: float64 - name: bed_bath_ratio dtype: float64 - name: ConvertedLot dtype: float64 - name: property_type dtype: string - name: is_good_flip dtype: int64 - name: Latitude dtype: float64 - name: Longitude dtype: float64 --- ## 🎥 Project Walkthrough Video <video src="https://huggingface.co/datasets/dant555/flipfinder-usa/resolve/main/flipfinder_presentation.mp4" controls="controls" style="max-width: 720px;"></video> # 🏠 FlipFinder USA ### Identifying Undervalued Real Estate Investment Opportunities Across the United States **Author:** Dan | **HuggingFace:** [@dant555](https://huggingface.co/dant555) --- ## 📋 Project Overview This project transforms a general-purpose Zillow real estate dataset into a focused investment screening tool. Using Exploratory Data Analysis (EDA), I engineered a binary target variable (`is_good_flip`) to identify properties that are genuinely underpriced relative to their immediate local market - potential candidates for a buy-renovate-sell (flip) investment strategy. --- ## ❓ The Question I Want to Answer > **Should I buy this property or not (is it a good real estate flip opportunity)?** --- ## 📦 Dataset - **Source:** [United States House Listings: Zillow Extract 2023](https://www.kaggle.com/datasets/febinphilips/us-house-listings-2023) - Kaggle - **Raw size:** 24,000+ rows × 16 features - **Cleaned size:** ~19,877 rows × 14 features (11 from Original + 3 New) - **Type:** Numeric tabular data ### Key Features | Feature | Type | Description | |---|---|---| | State | Categorical | 2-letter US state abbreviation (e.g. CA, NY, TX) | | City | Categorical | City in which the property is located | | Zipcode | Categorical | 5-digit US ZIP code, stored as string to preserve leading zeros | | Price | Numerical | Listed asking price of the property in USD | | Area | Numerical | Interior living area measured in square feet | | PPSq | Numerical | Price per square foot, calculated as Price / Area | | Bedroom | Numerical | Number of bedrooms in the property | | Bathroom | Numerical | Number of bathrooms, including half baths (e.g. 1.5, 2.5) | | bed_bath_ratio | Numerical | Ratio of bedrooms to bathrooms, proxy for layout density | | ConvertedLot | Numerical | Lot size in acres, missing for many urban/condo properties | | property_type | Categorical | Size-based category: Condo/Small Property, Townhouse, Small Family Home, Large Family Home | | is_good_flip | Categorical | Binary target variable: 1 = Good Flip Opportunity, 0 = Not a Good Flip | | Latitude | Numerical | Geographic latitude coordinate for spatial mapping | | Longitude | Numerical | Geographic longitude coordinate for spatial mapping | --- ## 🎯 Target Variable - `is_good_flip` Since the dataset has no built-in classification target, I engineered my own binary label. My first instinct was to use Zillow's `zestimate` column as the benchmark - but 8,594 values were missing, making it unreliable. Instead, `is_good_flip` is defined as follows: - Calculate each property's **Price Per Square Foot (PPSq)** - Group by **5-digit ZIP + Bedroom count** to find the local market median (minimum 5 properties) - Fall back to **5-digit ZIP only** if the primary group is too small - Fall back to **3-digit ZIP prefix** if still too small - Label **1 (Good Flip)** if PPSq is ≥ 15% below the local median - Label **0 (Not a Good Flip)** otherwise **27.3%** of properties were labeled as good flip opportunities. --- ## 🧹 Section 2: Data Wrangling - Dropped columns with excessive missing values (`MarketEstimate`, `RentEstimate`) and redundant columns (`LotArea`, `LotUnit`, `Street`) - Dropped rows with missing values in 8 critical columns: `Price`, `Area`, `PPSq`, `Bedroom`, `Bathroom`, `Zipcode`, `Latitude`, `Longitude` - Restored East Coast ZIP codes with leading zeros (e.g. `02886`) lost during float conversion - Validated all coordinates within US geographic boundaries (including Alaska) - Applied 7 domain-specific filters to focus on realistic flip candidates: - Price: $50,000 - $2,000,000 - Area: 400 - 5,000 sqft - PPSq: $10 - $2,000 - Bedrooms: 1 - 8 - Bathrooms: 1 - 5 - Bed/Bath ratio: ≤ 4:1 - Lot size: 0.01 - 5 acres **Before cleaning - outliers clearly visible across all features:**  **After cleaning - distributions are tighter and more meaningful:**  --- ## 🔄 Section 3: Data Transformation Both `Price` and `PPSq` were identified as strongly right-skewed distributions. To normalize them, I applied a log transformation using `np.log1p`, storing the results as `log_Price` and `log_PPSq` for potential future modeling use. All EDA and business analyses continue to use the original dollar values for interpretability. --- ## ⚙️ Section 4: Feature Engineering To enrich the dataset for analysis, I engineered two new columns. The binary target variable `is_good_flip` is fully described in the Target Variable section above. Additionally, I created `property_type`: a categorical column classifying each property into one of four size-based categories based on living area: Condo/Small Property (under 800 sqft), Townhouse (800-1,500 sqft), Small Family Home (1,500-2,500 sqft), and Large Family Home (above 2,500 sqft). ## 📊 Section 5: Descriptive Statistics To understand relationships between features, I generated a correlation heatmap across all numeric variables including the target variable `is_good_flip`. This revealed that no single feature has a strong linear correlation with the target - suggesting the flip signal is driven by a combination of variables rather than any one feature alone.  > The weak individual correlations with `is_good_flip` are not a problem - they reflect that flip opportunity is a threshold-based, hyper-local signal that linear correlation cannot capture. --- ## 📈 Section 6: Exploratory Visualization **Price Distribution:** The listing price distribution is strongly right-skewed, with most properties clustered between $100K and $600K. The median price of $335,000 sits well below the mean of $390,550, confirming the right skew caused by a tail of higher-priced properties.  > The peak of the distribution falls around $250K-$300K - the sweet spot for realistic flip investment candidates. --- **Properties by State:** The waffle chart displays all 49 represented US states, with each square colored by its good flip rate. The dataset is well balanced across states, with between 280 and 480 properties per state.  > Flip rates range from 17.5% to 37.6% across states - a 20 percentage point spread confirming that geography is a meaningful variable worth investigating further. --- ## 🔍 Section 7: Bivariate Exploration **PPSq Distribution by Flip Status:** I compared the price per square foot distribution between good flip and non-flip properties to verify the target variable is working correctly and that the two groups are meaningfully separated.  > Good flip properties have a median PPSq of $119/sqft vs $206/sqft for non-flips - a clear and significant separation confirming the target variable is well-engineered. --- **Feature Distributions by Flip Status:** I examined how Price, Area, Bedroom, and Bathroom distributions differ between good flip and non-flip properties using violin plots to show the full distribution shape of each group.  > Good flips have a significantly lower median price ($239,900 vs $365,000) and slightly larger area (2,040 vs 1,750 sqft). Bedroom and bathroom counts are identical across both groups - confirming layout alone does not drive the flip signal. --- **Bed/Bath Ratio & Flip Rate:** I examined whether the bedroom-to-bathroom ratio - a proxy for layout density and renovation age - is associated with higher flip rates across five ratio categories.  > Dense layouts with a ratio above 3.0 show a 53.7% flip rate - nearly double the dataset average of 27.3% - confirming that older, under-renovated homes are systematically underpriced in their local markets. --- **Threshold Validation:** To verify that the 15% threshold used to define `is_good_flip` is well-calibrated and not arbitrary, I visualized the actual PPSq deviation from local median for both groups.  > The typical good flip sits at -29.8% below its local median - nearly double the 15% minimum - confirming the threshold is conservative and creates a clean, meaningful separation between the two classes. --- ## ❓ Section 8: Multivariate Exploration & Research Questions ### Q1 - Which ZIP codes have the highest concentration of good flip opportunities? I calculated the flip rate for every ZIP code with at least 10 properties to ensure statistical reliability, then ranked the top 15 performers.  > ZIP code 58554 (ND) leads at 47.1%, followed by 19975 (DE) and 02886 (RI) both at 46.2%. Every ZIP code in the top 15 exceeds the dataset average by at least 13 percentage points - confirming that micro-market selection is critical for investors. --- ### Q2 - Which states offer the most good flip opportunities? I mapped the good flip rate for all 49 states on an interactive choropleth map to reveal geographic clustering patterns that a table or bar chart cannot convey.  > Maine (37.6%), Oregon (33.8%), and Vermont (33.6%) lead all states. Nevada (17.5%) is the weakest market. A clear Northeast and Pacific Northwest vs Sun Belt divide emerges - Sun Belt states that experienced rapid price appreciation show the lowest flip rates. --- ### Q3 - What does a typical good flip opportunity look like? I used a 2D KDE contour plot to map the concentration of good flip opportunities in the Price vs Area space, revealing where flip candidates cluster most densely.  > Good flip opportunities cluster tightly around $237,000 and ~2,000 sqft. Properties above $500K become increasingly rare as flip candidates regardless of size or layout - confirming that good flips are concentrated in the affordable, mid-size segment of the market. --- ### Q4 - Which layout is most associated with good flip opportunities? I calculated the good flip rate for each property type category to understand whether property size influences the likelihood of a listing being underpriced relative to its local market.  > Large Family Homes above 2,500 sqft show the highest flip rate at 37.2% - nearly three times higher than Condo/Small Properties at 13.0%. Larger, older homes with dense bedroom layouts are the prime flip targets, likely because they require more renovation capital which suppresses buyer competition. --- ### 🗺️ Geographic Distribution of Good Flip Opportunities I plotted every good flip property on an interactive US map, encoding PPSq as color and listing price as bubble size, to provide a direct investment screening tool.  > Good flip opportunities exist nationwide. Dark green dots (low PPSq) dominate the Midwest and South, representing the most affordable entry points. The single large red dot on the West Coast captures a rare high-PPSq flip in an expensive urban market. --- ## 📝 Section 9: Communication of Insights **Finding 1 - Geography is the strongest driver** The most powerful predictor of flip opportunity is geographic location. Maine leads all states at 37.6% while Nevada sits at the bottom at just 17.5% - a 20 percentage point gap. The Northeast and Pacific Northwest consistently outperform the Sun Belt, where recent price appreciation has reduced the availability of underpriced listings. At the micro-market level, ZIP code 58554 (ND) leads all areas at 47.1%, followed by 19975 (DE) and 02886 (RI) both at 46.2%. Every ZIP code in the top 15 exceeds the dataset average by at least 13 percentage points, confirming that micro-market selection is as important as state-level selection. **Finding 2 - Property size and type drive flip rate** There is a clear and consistent relationship between property size and flip opportunity rate. Large Family Homes above 2,500 sqft have a flip rate of 37.2% - nearly three times higher than Condo/Small Properties at 13.0%, with Townhouses at 19.6% and Small Family Homes at 28.3% falling in between. Larger properties are more likely to be underpriced relative to their local market because they require more renovation capital, suppressing buyer competition and listing price below the local median. **Finding 3 - Layout efficiency is an independent flip signal** Beyond size, the bedroom-to-bathroom ratio adds a separate and even stronger signal. Dense layouts with a ratio above 3.0 reach a 53.7% flip rate - nearly double the dataset average - independently of property size. This ratio captures the renovation age and efficiency of a property in a way that size alone cannot. Properties with many bedrooms relative to bathrooms are hallmarks of older, under-renovated homes that have not kept pace with modern buyer expectations, creating systematic pricing gaps relative to their local market. **Finding 4 - The flip signal is threshold-based, not linear** The weak individual correlations observed in the heatmap are explained by the fact that `is_good_flip` is driven by the combination of price, area, and local market context - not by any single feature alone. Good flips cluster tightly below $237,000 and around 1,996 sqft, with a median PPSq of $119/sqft compared to $206/sqft for non-flips. The concentration is tight and well-defined, confirming that flip opportunities occupy a specific and narrow price-size window in the market. **Finding 5 - Price is the strongest individual separator** Among all individual features, listing price shows the clearest separation between good flip and non-flip properties. Good flip properties have a median price of $239,900 compared to $365,000 for non-flips - a difference of over $125,000. This tells investors that the typical good flip opportunity is concentrated in the affordable segment of the market, and properties priced above $500,000 become increasingly rare as flip candidates regardless of their size or layout. **Finding 6 - Lot size is not a predictor of flip opportunity** Unlike price, size, and layout - lot size shows virtually no difference between good flip and non-flip properties. Both groups share an identical median lot size of 0.25 acres and their distributions are nearly indistinguishable. This is a valuable null finding - it tells investors that filtering by lot size is not a useful screening criterion when searching for flip opportunities, and that their focus should remain on price per square foot relative to the local market median. --- ## ⚠️ Limitations - Dataset captures **listing prices**, not final sale prices - **Hawaii** is not represented in this extract - **Missing lot sizes** for many urban/condo properties - **Zestimate** had too many missing values to use as benchmark - Dataset is a **static 2023 snapshot** - market conditions may have changed - Local medians are based on **dataset sample**, not complete Zillow database --- ## 📁 Repository Contents | File | Description | |---|---| | `flipfinder_usa_cleaned.csv` | Cleaned dataset ready for analysis | | [Dan's_Assignment_1_EDA_&_Dataset.ipynb](https://colab.research.google.com/drive/1G8vJOB68FHK-YB_uBmcuU4qFs53yPg_y?usp=sharing) | Full EDA notebook with all code and explanations | | `Plots/` | Visualization images used in this README | ## 🚀 How to Run 1. Open the `.ipynb` file in Google Colab or Jupyter Notebook 2. Upload your `kaggle.json` credentials file when prompted 3. Run all cells from top to bottom 4. All visualizations and findings will be generated automatically --- *Project by Dan | FlipFinder USA | 2025*