Solal9/polymarket-crypto-updown-binary
收藏资源简介:
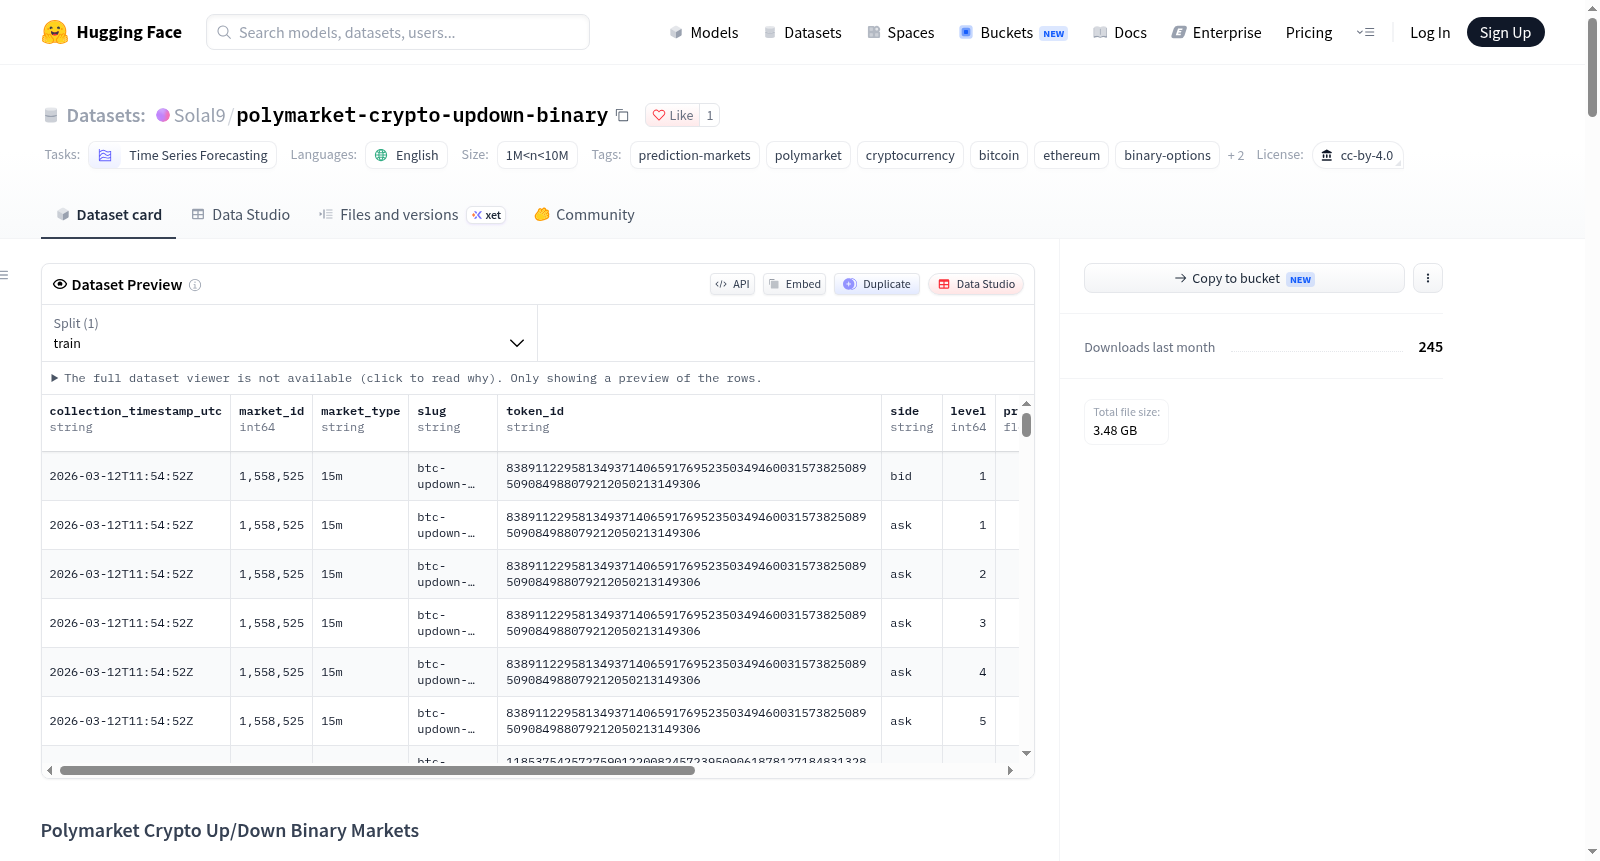
--- language: - en license: cc-by-4.0 task_categories: - time-series-forecasting tags: - prediction-markets - polymarket - cryptocurrency - bitcoin - ethereum - binary-options - finance - market-microstructure pretty_name: Polymarket Crypto Up/Down Binary Markets by Kresmion.com size_categories: - 1M<n<10M --- # Polymarket Crypto Up/Down Binary Markets Historical orderbook and market snapshot data from Polymarket's short-duration binary "Up or Down" prediction markets for BTC, ETH, SOL, and XRP. Collected continuously over approximately two months at 60-second polling intervals. This dataset captures something genuinely uncommon in publicly available crypto data: minute-resolution implied probabilities for 5-minute, 15-minute, hourly, and daily directional outcomes, with full top-of-book pricing and 5-level orderbook depth. This dataset was collected while building [Kresmion](https://kresmion.com), a financial intelligence platform ## What's in this dataset **4 assets:** BTC, ETH, SOL, XRP **4 timeframes:** 5m, 15m, 1h, 1d (1h and 1d markets are BTC-only on Polymarket) **Total markets covered:** thousands of resolved binary markets **Collection cadence:** 60-second polls **Time period:** [FILL IN: e.g. 2026-03-14 to 2026-05-20, with documented gaps] Two files per asset-timeframe pair: - **`<asset>_<timeframe>_snapshots.parquet`** — one row per poll: market metadata, top-of-book pricing, implied probability, depth summary, market-wide volume and liquidity - **`<asset>_<timeframe>_orderbook.parquet`** — one row per orderbook level per poll: full 5-level depth on both sides with cumulative size and USDC value ## Schema ### Snapshots | Column | Type | Description | |---|---|---| | `collection_timestamp_utc` | datetime | When this row was collected | | `market_id` | string | Polymarket internal market identifier | | `event_id` | string | Parent event identifier | | `condition_id` | string | Polymarket condition identifier (used on the CLOB) | | `slug` | string | Human-readable market slug, e.g. `btc-updown-5m-1773315900` | | `asset` | string | `btc`, `eth`, `sol`, `xrp` | | `question` | string | Full market question text | | `description` | string | Market description from Polymarket | | `market_category` | string | Polymarket category tag | | `window_start_unix` | int | Unix timestamp of the prediction window start | | `window_start_utc` | datetime | Window start in UTC | | `window_end_utc` | datetime | Window end in UTC | | `end_time` | datetime | Market end as reported by Gamma API | | `resolution_time` | datetime | UMA resolution time from Gamma API | | `active_status` | bool | Whether the market was active at collection time | | `closed_status` | bool | Whether the market was closed at collection time | | `market_type` | string | `5m`, `15m`, `1h`, `1d` | | `outcomes` | json | Outcome labels, e.g. `["Up","Down"]` | | `outcome_prices` | json | Outcome prices, e.g. `["0.54","0.46"]` | | `best_bid` | float | Top bid on the Yes/Up token | | `best_ask` | float | Top ask on the Yes/Up token | | `last_price` | float | Last traded price on the Yes/Up token | | `implied_probability` | float | Probability of the Up outcome | | `spread` | float | Bid-ask spread on the Yes/Up token | | `bid_depth_shares` | float | Total share depth across top-5 bid levels | | `ask_depth_shares` | float | Total share depth across top-5 ask levels | | `bid_depth_usdc` | float | USDC notional depth across top-5 bid levels | | `ask_depth_usdc` | float | USDC notional depth across top-5 ask levels | | `bid_levels_count` | int | Bid levels actually present (≤ 5) | | `ask_levels_count` | int | Ask levels actually present (≤ 5) | | `bid_vwap` | float | VWAP across captured bid depth | | `ask_vwap` | float | VWAP across captured ask depth | | `volume` | float | All-time market volume from Gamma API | | `volume_24h` | float | Trailing 24h market volume from Gamma API | | `liquidity` | float | Market liquidity from Gamma API | ### Orderbook | Column | Type | Description | |---|---|---| | `collection_timestamp_utc` | datetime | When this row was collected | | `market_id` | string | Polymarket internal market identifier | | `asset` | string | `btc`, `eth`, `sol`, `xrp` | | `market_type` | string | `5m`, `15m`, `1h`, `1d` | | `slug` | string | Human-readable market slug | | `token_id` | string | CLOB token identifier (Up or Down side) | | `side` | string | `bid` or `ask` | | `level` | int | 1 = best price, increasing toward worse prices | | `price` | float | Price at this level | | `size` | float | Shares available at this level | | `usdc_value` | float | `price × size` | | `cumulative_size` | float | Running total of shares from level 1 to this level | | `cumulative_usdc` | float | Running total of USDC from level 1 to this level | ## How the data was collected A Python collector polled two of Polymarket's public APIs every 60 seconds: - **Gamma API** (`https://gamma-api.polymarket.com`) — market metadata, volume, liquidity - **CLOB API** (`https://clob.polymarket.com`) — live orderbook depth Both endpoints are public and require no authentication. The collector respected standard HTTP retry-after headers and used connection pooling to minimize load. ### Market identification Polymarket uses two different slug formats for Up/Down markets depending on timeframe: **Format A** — unix timestamp suffix (5m and 15m markets): btc-updown-5m-1773315900 btc-updown-15m-1773315900 The window start is computable as `floor(now / window_seconds) * window_seconds`. No API discovery is needed because slugs are fully deterministic. **Format B** — human-readable date/time suffix (1h and 1d markets): bitcoin-up-or-down-march-14-10am-et (1h) bitcoin-up-or-down-on-march-14 (1d) 1h markets use Eastern Time with 12-hour clock and no leading zero. 1d markets use UTC date of the market end day. Both formats pre-create multiple future windows, so the collector generated current + next N window slugs per cycle to capture the transition when one market resolves and the next becomes active. ### Polling behavior For each market, the collector fetched: 1. Market metadata and volume from Gamma 2. Live orderbook (5 levels each side) from CLOB 3. Computed depth aggregates (total shares, USDC, VWAP per side) Snapshots were appended to per-asset, per-timeframe CSV files. The original CSVs have been converted to Parquet for this release. ## Known limitations and gaps Honest disclosure of what this dataset is and isn't. **Gaps in collection.** The collector was not running continuously. Approximate gap periods: - [FILL IN: e.g. 2026-04-02 to 2026-04-08 (collector downtime)] - [FILL IN: e.g. 2026-04-19 to 2026-04-21 (network issue)] - [FILL IN: any other gaps] To identify gaps programmatically, look for periods where `collection_timestamp_utc` skips by more than ~120 seconds. **Orderbook depth limited to 5 levels per side.** Microstructure research requiring full book reconstruction will find this dataset insufficient. The depth captures the typical Polymarket orderbook well for short-duration markets but doesn't include deep tails. **Resolution outcomes.** [FILL IN: state whether the dataset includes final resolution outcomes for closed markets. If yes, describe which column holds it. If no, document the gap and suggest pulling from Polymarket's resolution endpoint via the `market_id` column.] **Coverage by asset.** ETH, SOL, and XRP only have 5m and 15m markets on Polymarket as of the collection period. Only BTC has 1h and 1d markets. The dataset reflects this — there are no `eth_1h_*`, `sol_1d_*`, etc. files. **Single collector.** Data was collected from a single source point. There is no cross-validation against an independent collector. **API rate limits.** During brief periods of high market activity, individual polls may have failed and retried. These show up as occasional gaps of 60-180 seconds rather than the standard 60-second cadence. ## Suggested analyses Things this dataset can support: - Information aggregation efficiency in very short-duration prediction markets (5-15 minute windows are particularly novel) - Comparing Polymarket implied probabilities against realized BTC/ETH/SOL/XRP returns at matching timeframes - Cross-asset correlation of binary market pricing during volatility regimes - Microstructure analysis: spread dynamics, depth resilience, response to underlying spot moves - Calibration studies: how well do market-implied probabilities match observed frequencies of Up vs Down outcomes - Bid-ask spread term structure across 5m, 15m, 1h, 1d horizons - Trading bot research and backtesting against historical orderbook state ## Loading the data ```python import pandas as pd # Single file snapshots = pd.read_parquet("btc_5m_snapshots.parquet") orderbook = pd.read_parquet("btc_5m_orderbook.parquet") # Or load via the Hugging Face datasets library from datasets import load_dataset ds = load_dataset("kresmion/polymarket-crypto-updown-binary") ``` ## License and use Released under **CC-BY-4.0**. You're free to use, modify, and redistribute this data for any purpose including commercial use, provided you give appropriate credit. The data was collected from Polymarket's public APIs which do not require authentication. Polymarket's Terms of Service apply to any downstream redistribution of the data they originated. If you redistribute this dataset or derivatives of it, please: 1. Credit the original collection ("Dataset collected via Polymarket public APIs") 2. Link back to this Hugging Face dataset page 3. Review Polymarket's current ToS for your specific use case ## Citation If you use this dataset in research or publication: ```bibtex @misc{kresmion2026polymarket, title = {Polymarket Crypto Up/Down Binary Markets Dataset}, author = {Kresmion}, year = {2026}, url = {https://huggingface.co/datasets/kresmion/polymarket-crypto-updown-binary} } ``` ## About This dataset was collected while building [Kresmion](https://kresmion.com), a financial intelligence platform that surfaces cross-asset signals from public filings, on-chain activity, derivatives positioning, and prediction markets. The collector ran as part of an experimental arbitrage research project; the dataset is being released because the underlying data is more broadly useful to researchers working on prediction market efficiency, short-duration directional pricing, and crypto microstructure. Kresmion publishes its full methodology at [kresmion.com/about/methodology](https://kresmion.com/about/methodology) and is free during beta.
Polymarket Crypto Up/Down Binary Markets is a historical orderbook and market snapshot dataset from Polymarkets short-duration binary Up or Down prediction markets for BTC, ETH, SOL, and XRP. Collected continuously over approximately two months at 60-second polling intervals, it provides minute-resolution implied probabilities for 5-minute, 15-minute, hourly, and daily directional outcomes, with full top-of-book pricing and 5-level orderbook depth. The dataset includes two files per asset-timeframe pair: snapshots (one row per poll with market metadata, top-of-book pricing, implied probability, depth summary, market-wide volume and liquidity) and orderbook (one row per orderbook level per poll with full 5-level depth on both sides, cumulative size and USDC value). It supports research on prediction market efficiency, crypto microstructure, implied probability calibration, and more, and is released on Hugging Face under the CC-BY-4.0 license.