polymarket-arena-capture
收藏资源简介:
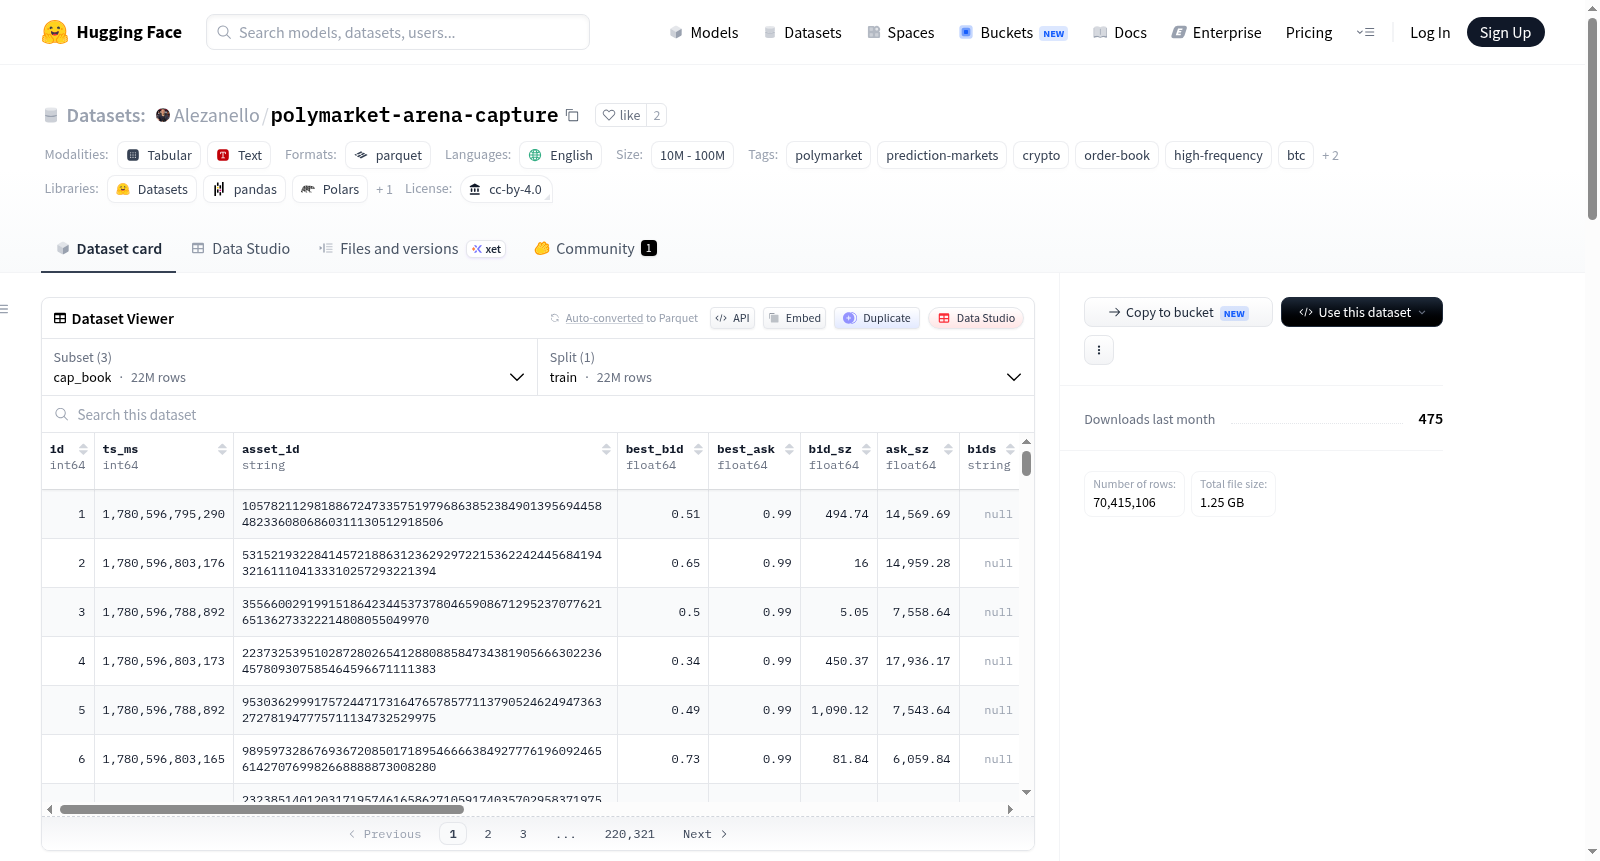
Polymarket Arena — Live Capture数据集是Polymarket短周期加密货币涨跌预测市场的原始实时市场数据集合。该数据集通过持续运行的WebSocket收集器捕获,订阅Polymarket的中央限价订单簿(CLOB)的交易与订单簿流以及实时数据流(RTDS)价格源,并将数据持久化存储至SQLite数据库,然后导出为无损Parquet格式(采用zstd 9级压缩)。数据窗口从2026年6月4日开始并持续更新(每日增长),保真度高,包含完整的原始数据行,未进行任何下采样或行过滤。数据涵盖BTC、ETH、SOL、XRP、BNB、DOGE等多种加密货币在5分钟、15分钟和1小时时间框架下的“涨/跌”市场。数据集包含三个核心表:`cap_trades`表记录在Polymarket CLOB上已执行的交易,包含交易ID、时间戳、资产ID、价格(概率值)、数量、买卖方向、底层资产、结果方向、市场slug、条件ID、窗口开始与结束时间等字段;`cap_book`表提供订单簿快照(包括买卖盘最优价和深度数据),以约2秒的节奏为每个代币捕获,包含最优买卖价、买卖盘数量、深度阶梯数据(JSON格式)等;`cap_prices`表记录底层现货或参考价格的实时跳动数据,包含来源(如币安、Chainlink)、资产、价格值和原始载荷JSON。数据布局采用混合模式:根目录下的`<表名>.parquet`文件包含初始回填数据(2026-06-04至06-15),而`daily/<表名>/<UTC时间>.parquet`目录则包含此后每日追加的增量数据。加载任一配置即可获得完整连续历史。需要注意的是,时间戳`ts_ms`为捕获时间(收集器时钟),而非交易所匹配时间;交易价格`price`为0到1之间的概率值,代表事件发生的预估概率;该数据集为纯粹的观测性市场数据,不包含任何代理或策略标签。该数据集适用于预测市场分析、高频交易研究、订单簿建模、市场微观结构分析以及加密货币价格与预测市场关联性研究等任务。
The Polymarket Arena — Live Capture dataset is a collection of raw real-time market data from Polymarkets short-term cryptocurrency up/down prediction markets. It is captured through a continuously running WebSocket collector that subscribes to Polymarkets Central Limit Order Book (CLOB) trade and order book streams, as well as Real-Time Data Stream (RTDS) price feeds, with data persisted in an SQLite database and exported in a lossless Parquet format (using zstd level 9 compression). The data window starts from June 4, 2026, and is continuously updated (growing daily). The dataset has high fidelity, containing complete raw data rows without any downsampling or row filtering. It covers multiple cryptocurrencies such as BTC, ETH, SOL, XRP, BNB, and DOGE across 5-minute, 15-minute, and 1-hour time frames for up/down markets. The dataset includes three core tables: the `cap_trades` table records executed trades on the Polymarket CLOB, with fields like trade ID, timestamp, asset ID, price (probability value), quantity, buy/sell direction, underlying asset, outcome direction, market slug, condition ID, window start and end times; the `cap_book` table provides order book snapshots (including best bid/ask prices and depth data) captured approximately every 2 seconds per token, containing best bid/ask, bid/ask quantities, depth ladder data (in JSON format); and the `cap_prices` table records real-time tick data for underlying spot or reference prices, including sources (e.g., Binance, Chainlink), asset, price value, and raw payload JSON. The data layout uses a hybrid pattern: `<table_name>.parquet` files in the root directory contain initial backfilled data (from 2026-06-04 to 06-15), while the `daily/<table_name>/<UTC_time>.parquet` directory includes daily incremental data appended thereafter. Loading any configuration provides complete continuous history. Note that the timestamp `ts_ms` is the capture time (collector clock), not the exchange matching time; the trade price `price` is a probability value between 0 and 1, representing the estimated probability of event occurrence; this dataset is purely observational market data without any agent or strategy labels. It is suitable for tasks like prediction market analysis, high-frequency trading research, order book modeling, market microstructure analysis, and studies on the correlation between cryptocurrency prices and prediction markets.